myFICO - Credit Score Tracking
FICOFinanceVerified
- 4.47K Reviews
- 4.3
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
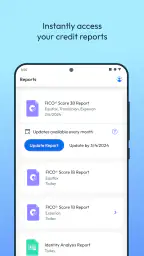
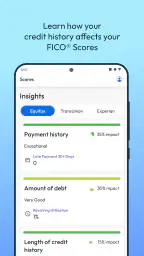
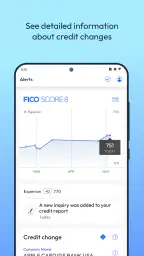
 Analysis by Appwesome
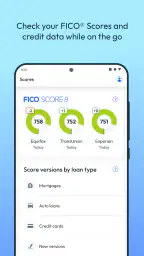
I look at credit information differently when I can see it in one place instead of trying to remember which bureau supplied which number. That is the main appeal of myFICO: it is a finance app from FICO focused on helping people view a FICO Score and an Equifax credit report for decisions involving credit cards, mortgages, and loans. I found it most useful as a monitoring and preparation tool, rather than as a complete personal-finance dashboard.
The app is free to install, carries an Everyone age rating, and has built a sizeable audience on mobile, with more than a million installs and an average score of 4.3 from roughly twelve thousand ratings. Those figures suggest that it has become a familiar option for people who specifically want FICO-oriented credit information. Still, popularity does not make credit data simple, and the experience requires a little patience if you want to understand what you are seeing rather than just glance at a number.
How myFICO feels to use today
My first impression is that this is a focused app. It is not trying to replace a budgeting app, bank app, bill calendar, or debt payoff planner. Its purpose is narrower: give you access to your credit score and Equifax report so you can review the information lenders may consider when you apply for borrowing.
That focus is helpful when I am preparing for a specific financial decision. If I am considering a new card, refinancing, or a mortgage application, I would rather inspect my credit profile before submitting an application than discover an error afterward. The app gives that preparation a clear destination: check the score, read the report, and look for anything that needs attention.
The important distinction is between a score and the report behind it. A score is a convenient summary, but the report contains the account history, balances, payment records, inquiries, and other details that can explain why the number looks the way it does. I would not use myFICO responsibly by opening it only to admire a score. The more valuable habit is to treat the score as a starting point and then read the underlying report carefully.
FICO is also the developer, which matters because the app is built around FICO scoring rather than presenting an unexplained number from an unrelated scoring model. That does not mean every lender will use the exact same score or version when reviewing an application. It does mean the app is aimed at users who want a FICO-centered view instead of relying only on a generic credit-monitoring estimate.
What the app is genuinely good at
The strongest use case is checking your position before a major application. Imagine that I am planning to apply for a mortgage in a few months. I could use the app to review my Equifax report, confirm that accounts belong to me, check whether balances look current, and make a note of anything that deserves follow-up. That is more useful than waiting until a lender raises a question.
Other Stories to Read




A second practical use is after a payment or account change. If I have paid down a card, closed an account, or noticed a suspicious entry, I can return to the report and compare what is displayed with my own records. I would not expect every change to appear instantly, because credit reporting depends on when information is sent and processed. The app is therefore best used as a regular checkpoint, not as a live transaction ledger.
A third use is learning how your borrowing behavior is represented. People often know that late payments or high balances matter, but the report helps connect those broad ideas to actual accounts. Reading it can reveal that an old address, unfamiliar inquiry, or incorrectly reported balance deserves attention. That kind of review is easy to postpone, which is why having a dedicated place to check can be valuable.
I also like the app for separating two decisions that people often mix together. First, should I apply for credit at all? Second, if I apply, is my profile accurate and in reasonable shape? myFICO can help with the second question and inform the first, but it cannot make the lending decision for you. A healthy-looking score is not a promise of approval, and a lower score does not explain every factor a lender may weigh.
Why the report deserves more attention than the headline score
When I review a credit report, I start with identity and account accuracy before thinking about improvement. I look for accounts I do not recognize, payment statuses that seem wrong, unusual inquiries, and balances that do not match recent statements. This order matters: there is little value in planning a long-term credit strategy around information that may be inaccurate.
My practical tip is to keep a small note outside the app while reviewing. I record the account name, the issue I noticed, the statement or document that supports my concern, and the date I checked it. That turns a vague feeling that “something looks off” into a useful record for follow-up. The app can show the information, but I still need to organize my own evidence and contact the appropriate party when necessary.
Another useful habit is checking before, not during, a major application. If I discover a problem on the day I plan to apply, I have less time to investigate it and may feel pressured into submitting an application anyway. Reviewing earlier gives me room to correct personal records, ask questions, or reconsider the timing of the application.
There is also a trade-off in focusing on Equifax. That bureau-specific view is useful if Equifax information is the part I need to inspect, but it is not a complete picture of every bureau’s records. A lender may receive information from another bureau or use a scoring model that differs from the one I am viewing. I would use this app as one important reference, not as proof that all credit files everywhere are identical.
What has changed and what that means for existing users
The current app version is 4.0.23.4, and its release history places the product in a mature stage rather than an early experiment. The app was first released on August 18, 2015, so existing users are returning to a service with years of development behind it. That history is reassuring in one sense: the basic purpose is established and easy to understand. It also means longtime users may notice that the modern experience is more about refinement and access than about discovering an entirely new type of credit tool.
For someone upgrading from an older installation, I would pay attention to how the current version handles sign-in, report access, and navigation rather than assuming every screen will feel familiar. Financial apps can change their presentation even when the underlying job stays the same. Before relying on it for an urgent application, I would open the app, make sure I can reach the information I need, and confirm that my account access works normally.
The app requires iOS or Android 12, which is a meaningful practical detail for anyone using an older phone. On a supported device, that requirement should not be a concern, but it can affect people who keep an older handset specifically for financial apps. I would check the operating system before planning to use myFICO as part of a time-sensitive credit review.
For existing users, the main benefit of the current version is continuity around the core workflow: open the app, access the FICO Score and Equifax report, then review the details. The limitation is that version progress does not remove the need for financial judgment. A newer interface cannot tell me whether an unfamiliar account is fraudulent, whether a lender will approve an application, or whether paying down one balance is the right move for my wider situation.
Where the experience still has friction
The first limitation is conceptual rather than technical: credit scores are easy to overinterpret. If the app puts a prominent score in front of me, I may be tempted to treat it as a final verdict. It is not. Scores can vary by bureau, scoring model, and the information available at the time. I would read the report and consider the timing of the information before drawing conclusions.
The second limitation is scope. Someone looking for spending categories, automatic budget planning, savings goals, investment tracking, or bill reminders will need another app. myFICO is not the right choice when the main question is “Where did my money go this month?” It is better suited to “What does my credit file currently show, and what should I inspect before borrowing?”
The third issue is that monitoring is not the same as correction. Finding an error is only the beginning. I may need to contact a creditor, gather statements, or follow a dispute process. The app can make a problem visible, but visibility does not guarantee a quick resolution. That is why I would avoid treating a credit-monitoring app as a substitute for keeping account records and responding directly to the organizations involved.
I would also be cautious about using the app as a source of instant reassurance after making a payment. A payment can be completed in my bank account while the credit report still reflects the previous reporting cycle. If I need a precise answer about whether a lender will see a change, I would ask the creditor or lender about its reporting timing instead of assuming the app updates immediately.
Finally, the app is most useful to people who are willing to read financial information carefully. If I only want a simple color indicator or a notification telling me that everything is fine, the report may feel more detailed than necessary. That detail is a strength for preparation, but it can feel like work for casual users.
How it compares with everyday alternatives
Many banking and credit-monitoring apps show a score as part of a broader account experience. Those alternatives can be convenient because they combine credit information with transactions, balances, alerts, and budgeting. If I already live inside my bank’s app and only want a quick snapshot, I may prefer that convenience.
myFICO makes more sense when I specifically want a FICO-oriented view and an Equifax report rather than a score presented without much context. Compared with a general budgeting app, it offers a deeper credit-review purpose. Compared with checking a report only when applying for a loan, it encourages a more deliberate habit of reviewing the file ahead of time.
That comparison also exposes its boundary. I would not install it expecting a full financial command center. I would pair it with a budgeting tool if I needed help managing daily cash flow, and I would consult other official or lender-provided sources when a particular application depends on a different bureau or scoring model. The best setup may be more than one tool, with each used for the job it actually handles well.
Who should use it and who should skip it
I recommend myFICO to someone preparing for a mortgage, auto loan, or new credit card who wants to inspect credit information before applying. It is also a sensible choice for a person rebuilding credit who wants to connect account activity with the information appearing on a report. The free price makes it easy to try without treating the installation itself as a financial commitment.
It can also help a cautious user establish a recurring review routine. I would choose a calm time, open the report, check for unfamiliar activity, compare important balances with recent statements, and write down follow-up actions. The routine is more valuable than opening the app repeatedly without knowing what I am looking for.
I would skip it, or at least avoid making it my only tool, if I mainly need budgeting, investment management, or a complete view across multiple credit bureaus. I would also avoid relying on it as an approval predictor. If a lender has told me which bureau or scoring model it uses, that information should guide my expectations more than any single score inside a mobile app.
What I would watch before making a financial decision
Before applying for credit, I would watch for three things: whether the report contains accurate accounts, whether recent balances and payment statuses look consistent with my records, and whether any inquiry or identity detail needs investigation. I would not rush from the score screen directly to an application.
I would also watch the timing of updates. A report is a snapshot of information that has been supplied and processed, not a live feed of every payment. If a recent action matters, I would allow appropriate reporting time and verify the result rather than assuming the first display tells the whole story.
For people upgrading from an older phone, I would check compatibility early because the current version requires iOS or Android 12. For people returning after a long break, I would test access before an urgent loan appointment. These are small steps, but they prevent a useful preparation tool from becoming a last-minute source of frustration.
Most importantly, I would watch my own interpretation. A score can guide a conversation, but the report supplies the detail and the lender makes the decision. That perspective keeps the app useful without asking it to promise more than credit monitoring can deliver.
After using it as a focused credit-checking tool, my opinion is positive but measured. myFICO is strongest when I use it to prepare, investigate, and understand my Equifax credit information, not when I expect it to manage every part of my financial life. Its mature history, free access, FICO focus, and clear relevance to borrowing make it worth considering for the right user.
I would recommend it to a friend who has a specific credit goal or wants a more informed review routine. I would explain that the score is only the headline, the report requires careful reading, and changes may not appear immediately. With those expectations, the app can turn a stressful credit check into a more organized process. Without them, it is easy to stare at one number and miss the information that actually needs attention.
Highlights
- Official FICO scores help users understand lender-focused credit data.
- Score history makes it easier to track changes over time.
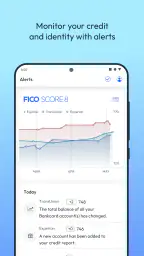
- Credit monitoring alerts can help identify possible identity theft.
- Personalized insights suggest ways to improve credit health.
- Secure account access supports convenient mobile credit management.
Limitations
- Many useful features require a paid subscription.
- FICO scores may differ from scores shown by other services.
- Frequent score updates can depend on the selected membership plan.
- Some users may find the amount of credit information overwhelming.
- The app requires sensitive financial and personal information.
Frequently Asked Questions
01What is myFICO - Credit Score Tracking used for?
myFICO - Credit Score Tracking is designed to help users monitor their FICO credit scores, review credit-report information, and understand the factors that may influence their credit profile. It can be useful when preparing for a loan, credit-card application, mortgage, or other financial decision. The app is primarily a monitoring and education tool, not a guarantee of approval or improved credit.
02Does the myFICO app provide the same credit score that lenders use?
myFICO focuses on FICO Scores, which are widely used by lenders, but the exact score a lender checks can vary. Different lenders may use different FICO versions, credit bureaus, industries, and calculation dates. As a result, the score shown in the app may not exactly match a score obtained during a credit application, even when both are legitimate FICO scores.
03Is myFICO - Credit Score Tracking free to download and use?
The app may be free to download, but access to full score reports, frequent updates, monitoring alerts, or additional credit information can depend on the membership plan selected. Before subscribing, review the current pricing, billing frequency, trial conditions, and cancellation policy shown in the app or official store listing. Availability and features may also differ by location and plan.
04How often are credit scores and reports updated in myFICO?
Update frequency depends on the myFICO subscription and the specific monitoring service included with it. Credit scores do not change simply because the app is opened; they usually change when new information is reported by lenders or when a new score is calculated. Users should also remember that creditors report on different schedules, so updates may not appear simultaneously.
05Is my personal and financial information safe when using myFICO?
myFICO handles sensitive information, so users should review its privacy policy, security practices, permissions, and account terms before creating an account. Use a strong, unique password and enable available security protections. The app can help monitor activity, but no service eliminates every risk. If you notice unfamiliar activity, contact myFICO and the relevant credit bureau promptly.


